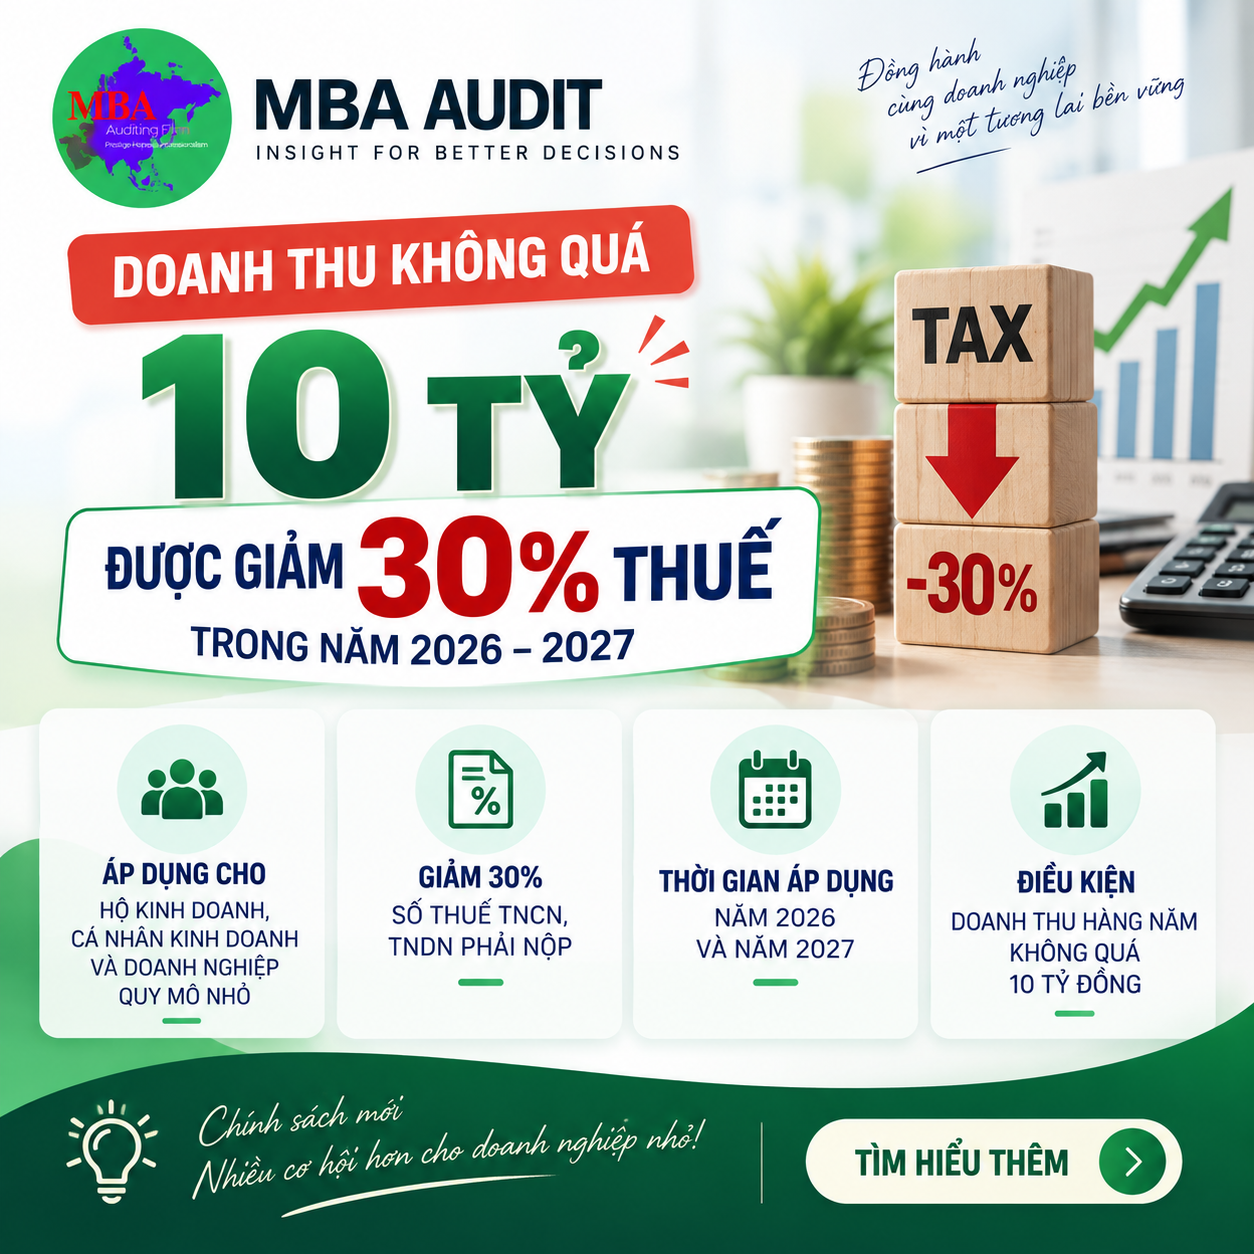
📌 REVENUE NOT EXCEEDING VND 10 BILLION: 30% TAX
REDUCTION IN 2026–2027?
On 24 August 2026, the National Assembly passed Resolution No. 43/2026/QH16 on the reduction of personal
income tax and corporate income tax for certain individuals and enterprises with annual revenue not exceeding
VND 10 billion.
This is a notable policy for business households, individual business operators and small-scale enterprises during
the 2026–2027 period.
So, who is eligible for the tax reduction, and what key points should be noted?
👤 1. Resident Individuals with Business Income
Resident individuals with business income are entitled to a 30% reduction in personal income tax payable for the
2026 and 2027 tax years, provided that their annual revenue for the respective year does not exceed VND 10 billion.
This group may include:
- ✅ Business households;
- ✅ Individual business operators;
- ✅ Resident individuals with income from business activities.
📍 Note: The revenue condition is assessed separately for each year.
Example:
🔹 Revenue of VND 8 billion in 2026: the revenue condition may be satisfied.
🔹 Revenue of VND 12 billion in 2027: the revenue condition for 2027 is not satisfied.
🏢 2. Enterprises and Organisations Established under the Laws
of Vietnam
Enterprises and organisations with annual revenue in 2026 or 2027 not exceeding VND 10 billion are entitled to:
👉 A 30% reduction in corporate income tax payable for the corresponding year.
⚠️ Important note: A 30% reduction in tax payable does not mean:
- ❌ A 30% reduction in revenue;
- ❌ A 30% reduction in taxable income;
- ❌ A 30% reduction in the tax rate.
For example, if the corporate income tax payable, as determined in accordance with applicable regulations,
is VND 100 million, the tax reduction amount is VND 30 million.
💡 3. Enterprises Currently Enjoying CIT Incentives
Where an enterprise is entitled to CIT incentives in accordance with applicable regulations, the 30% tax reduction
is calculated based on the CIT payable after applying the relevant tax incentives.
Therefore, enterprises should correctly determine the order of applying tax incentives and tax
reductions to avoid errors during tax finalisation.
⚠️ 4. Note on Enterprise Division or Separation
The tax reduction policy does not apply to enterprises formed through the division or separation of an enterprise
after the effective date of the Resolution, if the total annual revenue of the enterprises resulting from such division
or separation exceeds VND 10 billion in 2026 or 2027.
This regulation aims to prevent enterprises from being split solely for the purpose of satisfying the revenue condition.
📅 5. Effective Period
📌 Effective date of the Resolution: 24 August 2026.
📌 Applicable tax periods: 2026 and 2027.
It should be noted that the policy applies to the 2026 tax year, not merely to revenue or income generated from
the effective date of the Resolution.
✅ IMPORTANT NOTES FOR ENTERPRISES AND BUSINESS HOUSEHOLDS
- 🔹 Track revenue separately for 2026 and 2027;
- 🔹 Accurately determine the PIT or CIT payable before applying the tax reduction;
- 🔹 Review any CIT incentives currently being applied;
- 🔹 Pay attention to cases involving enterprise division, separation or reorganisation;
- 🔹 Continue to monitor the Government’s detailed implementation guidance.
📌 The most notable point of this policy is not merely the 30% reduction, but the fact that the VND 10 billion
revenue threshold is determined separately for each year.
Therefore, the same business may be eligible in 2026 but not in 2027, or vice versa.
📞 Does your business need to review its eligibility for the tax reduction?
Contact MBA Audit for support in reviewing your documents and advising on the appropriate approach.
#MBAAudit #NghiQuyet43 #GiamThue #ThueTNDN #ThueTNCN #HoKinhDoanh #CaNhanKinhDoanh #DoanhNghiepNho #ChinhSachThue2026
- OFFICIAL UPDATE: Monthly Personal Income Tax (PIT) filing has been discontinued effective May 8, 2026
- 📢 Dependent Accounting Representative Office – How to Declare Taxes Correctly?
- Tax Q&A for Household Businesses
- 🔍 ALL OVERTIME PAY WILL BE TAX-FREE FROM 2026 – RIGHT OR WRONG?
- 📢 DECREE NO. 255/2026/NĐ-CP: KEY UPDATES ON RELATED-PARTY TRANSACTIONS THAT ENTERPRISES SHOULD NOTE