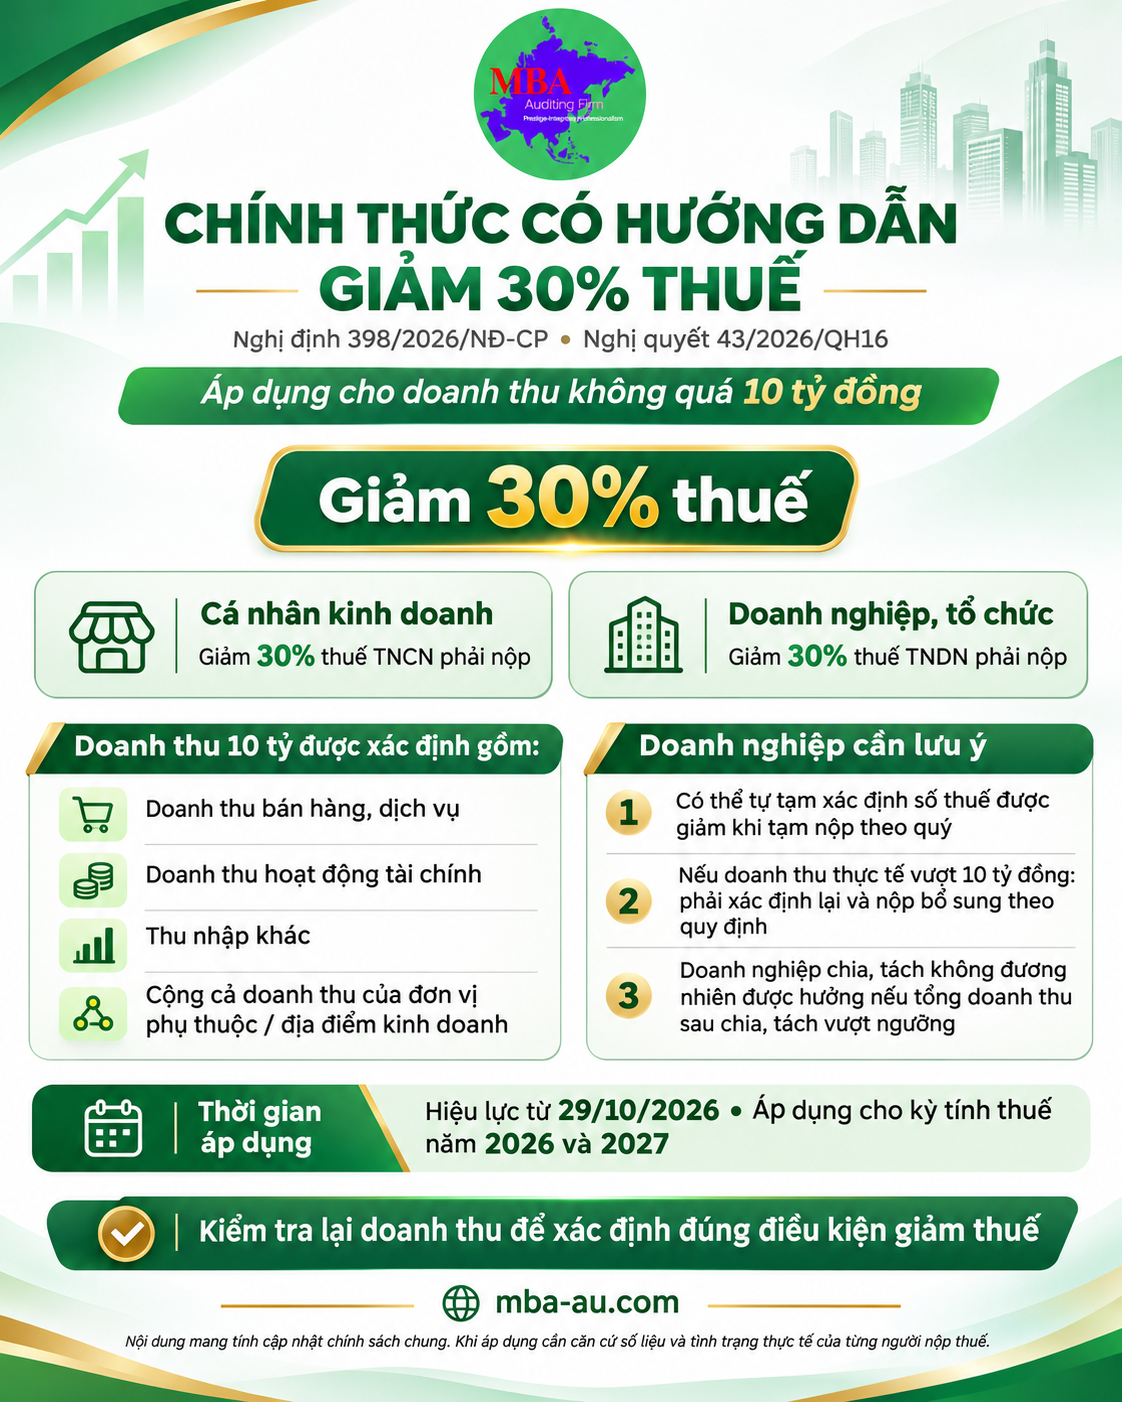
On 29 October 2026, the Government issued Decree No. 398/2026/ND-CP, providing detailed guidance on Resolution No. 43/2026/QH16 concerning Personal Income Tax (PIT) and Corporate Income Tax (CIT) reductions for 2026–2027.
The key development is not merely the 30% tax reduction, but the introduction of specific guidance on determining annual revenue and declaring the applicable tax reduction.
👤 1. INDIVIDUAL BUSINESS OPERATORS
Resident individuals earning income from business activities whose annual revenue does not exceed VND 10 billion in either 2026 or 2027 are entitled to:
👉 A 30% reduction in the PIT payable for the corresponding year.
Where annual revenue is projected not to exceed VND 10 billion, the individual may declare the tax reduction using Form No. 01 attached to the Decree.
Where an organisation or individual withholds, declares or pays tax on behalf of the taxpayer, Form No. 02 must be used.
⚠️ Important:
If actual annual revenue ultimately exceeds VND 10 billion, the individual will no longer qualify for the tax reduction and must:
- Submit an amended tax declaration;
- Pay the additional tax corresponding to the reduction previously claimed;
- Use Form No. 03 as prescribed.
For additional tax payable solely as a result of reassessing eligibility for the reduction, late-payment interest will not be charged up to the tax filing deadline for the period in which cumulative revenue exceeds VND 10 billion.
🏢 2. ENTERPRISES AND OTHER ORGANISATIONS
Enterprises, cooperatives, public service units and other organisations established under Vietnamese law that conduct business activities and have annual revenue not exceeding VND 10 billion are entitled to:
👉 A 30% reduction in the CIT payable for the 2026 and 2027 tax periods.
Where an enterprise is already entitled to CIT incentives:
The 30% reduction is calculated on the CIT payable after applying the existing tax incentives.
🔎 3. HOW IS THE VND 10 BILLION REVENUE THRESHOLD DETERMINED?
This is a particularly important consideration for enterprises.
Annual revenue for determining eligibility for the tax reduction includes:
- ✔ Revenue from sales of goods and provision of services;
- ✔ Financial income;
- ✔ Other income.
Where an enterprise has:
- Dependent units; or
- Business locations,
the revenue of these units or locations, as reflected in the enterprise’s annual aggregated financial statements, must also be included when determining eligibility.
👉 Therefore, enterprises should not rely solely on the revenue recorded in a single sales revenue account when concluding that their annual revenue falls below the VND 10 billion threshold.
📊 4. HOW SHOULD ENTERPRISES PROVISIONALLY DETERMINE THE TAX REDUCTION?
Where an enterprise expects its annual revenue for 2026 or 2027 not to exceed VND 10 billion, it may:
👉 Self-assess the applicable CIT reduction when making quarterly provisional CIT payments.
However, eligibility must be reassessed based on actual annual revenue at year-end.
If actual annual revenue exceeds VND 10 billion, the enterprise will not qualify for the reduction and must reassess its tax obligations in accordance with the applicable regulations.
⚠️ 5. ENTERPRISES FORMED THROUGH DIVISION OR SEPARATION ARE NOT AUTOMATICALLY ELIGIBLE
The tax reduction does not apply to enterprises established through a division or separation after Resolution No. 43/2026/QH16 takes effect if:
👉 The combined annual revenue of all enterprises formed following the division or separation exceeds VND 10 billion.
The combined revenue must include the revenue of all enterprises formed from the division or separation of the original enterprise.
🧾 6. WHAT HAPPENS WHEN TAX LIABILITIES CHANGE FOLLOWING AMENDED DECLARATIONS OR INSPECTIONS?
Where supplementary tax declarations or the findings of an inspection, examination or audit result in:
An increase in tax payable
➡️ The additional tax payable may still qualify for the 30% reduction, provided the enterprise or individual continues to satisfy the eligibility requirements.
A decrease in tax payable
➡️ The amount of the tax reduction must be adjusted accordingly.
📅 7. EFFECTIVE DATE AND APPLICABLE TAX PERIODS
Decree No. 398/2026/ND-CP takes effect on 29 October 2026 and applies to:
- 📌 The 2026 tax period
- 📌 The 2027 tax period
✅ KEY ITEMS ENTERPRISES SHOULD REVIEW NOW
If annual revenue is approaching the VND 10 billion threshold, enterprises should look beyond sales revenue alone.
The following items should be reviewed:
- 🔹 Revenue from sales of goods and provision of services;
- 🔹 Financial income;
- 🔹 Other income;
- 🔹 Revenue of dependent units and business locations;
- 🔹 Corporate reorganisations, divisions and separations.
📌 The key to this policy is not simply the 30% tax reduction itself, but accurately determining annual revenue to establish whether the taxpayer genuinely qualifies for the relief.
This article provides a general update on tax policy. Its application should be assessed based on each taxpayer’s actual financial information and specific circumstances.
#MBAAudit #Decree398 #TaxReduction #CorporateIncomeTax #PersonalIncomeTax #SmallBusinesses #HouseholdBusinesses #VietnamTaxPolicy2026
- Circular 99/2025/TT-BTC – The End of the Accounting Era Where “All burdens fall on one person”
- 📌 23 ALLOWANCES: WHICH ARE SUBJECT TO SOCIAL INSURANCE CONTRIBUTIONS? WHICH ARE PIT-EXEMPT?
- VAT Changes in Vietnam After July 1, 2025 – What Businesses Must Know
- Decree 228/2025/ND-CP – Mandatory Audited Financial Statements
- 🎄 CHRISTMAS IS COMING – AND SO IS THE AUDIT CONTRACT DEADLINE!